Machine Learning
Regression baselines, stationarity tests, and walk-forward evaluation on daily BTC prices.
Notebook with recorded results; the demo re-runs the models on the repository's dataset.
pandasscikit-learnstatsmodelsTypeScript (demo)
Overview
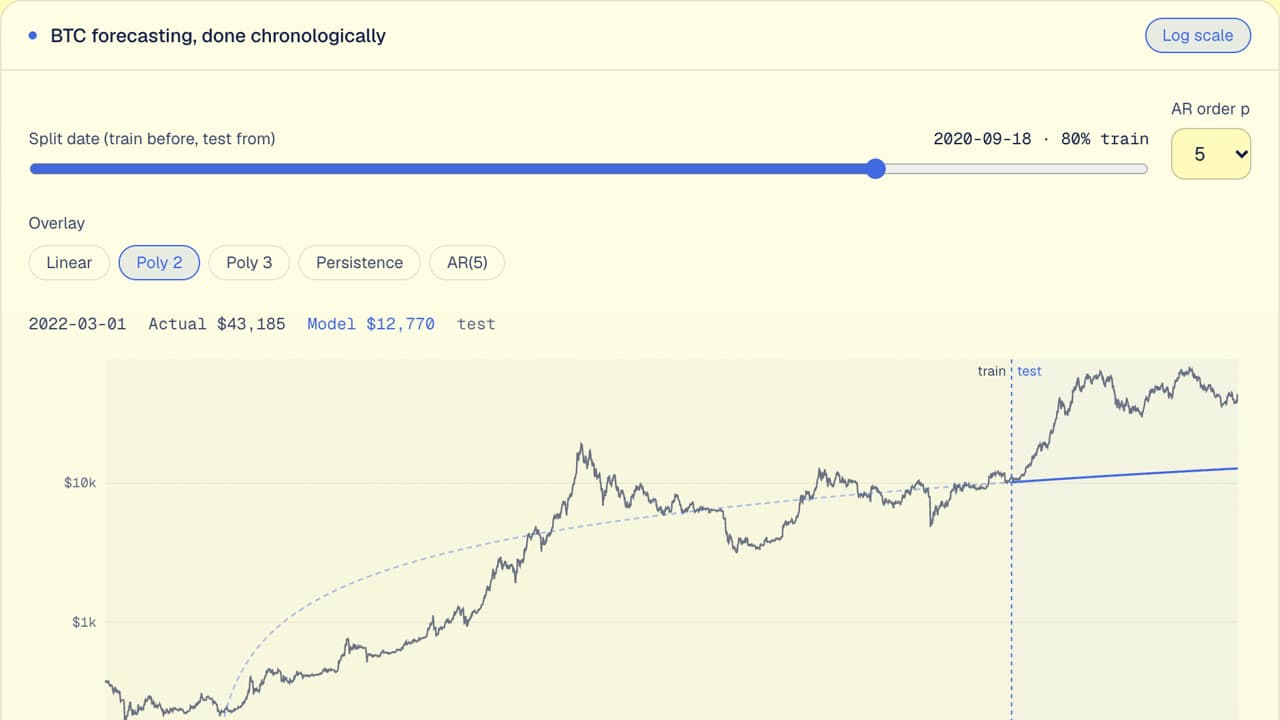
Forecasting daily Bitcoin closing prices with linear and polynomial regression on time, Augmented Dickey-Fuller stationarity tests, ACF and PACF analysis, and rolling-window evaluation.
Interactive demo
Uses the repository's BTC-Daily.csv (2,651 days). Unlike the notebook's random split, the demo evaluates chronologically, which is the correct protocol for time series.
Recorded results
- Linear regression RMSE
- 10,160.62
- Random 80/20 split
- Source: i2112697_A4.ipynb, cell 7
- Polynomial (deg 2) RMSE
- 7,444.31
- Random 80/20 split
- Source: i2112697_A4.ipynb, cell 10
- ADF p-value, first difference
- 1.05e-13
- Close price p = 0.32 (non-stationary)
- Source: i2112697_A4.ipynb, cell 12